Boat crew coverage starts with who employs the crew.
Paying a captain or crew changes what your insurance has to answer. The first question is not which policy, but who employs them. We say which belong to the policy, which to a maritime attorney.
Crewed operations as a whole are on Charter Business Insurance; privately used boats with no paid crew on Yacht Insurance.
Who hires, pays and directs the crew.
The employer can be the owner, an owning company, a charter business or a management company. It can differ between captain and deckhands, and from one trip to the next. The arrangement shapes which legal rules apply and which policy should respond; a job title settles neither. We start with the paperwork: contracts, who pays and who can dismiss.
If you are a captain working under someone else's policy, ask that employer whether it approves you as captain, and put the employment questions to a maritime specialist.
Crew are not guests, and the rules treat them differently.
The federal passenger definition excludes qualifying paid working crew, so a crew injury is a different question from a guest injury. Four bodies of law can be involved: the Jones Act, maintenance and cure, the Longshore and Harbor Workers' Compensation Act and Florida workers' compensation. Which applies depends on the facts; marine employment needs specialist review.
Whether someone is a seaman is a legal question. When yours reaches that point we say so and suggest a maritime attorney. Who counts as a passenger is explained once, on Bareboat Charter.
Six questions to put to your policy about crew.
Questions to check, not products Rise offers.
- Does it describe paid crew at all? Some yacht policies do.
- Who is the insured employer? The entity that employs the crew should be the one named.
- Is the captain approved? Confirm before a new captain takes the helm.
- How does it treat delivery and repositioning, where the engagement, route and duties can change?
- What about day crew? Trip-by-trip hires may sit differently from permanent crew.
- Where is the gap? If no policy clearly answers a crew injury, raise that first.
Looking for a health or medical plan for crew? That is a different product and is not covered on this page.
Rise and your crew.
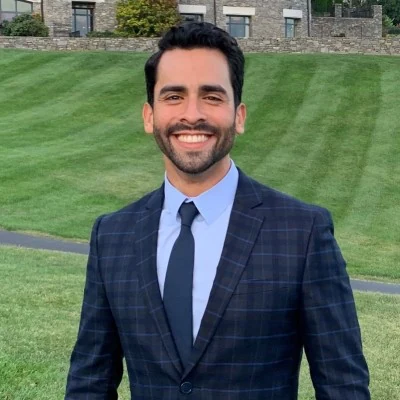
Roberto Guerrero, President and Principal Agent of Rise Specialized Insurance in Saint Petersburg, reads the crew arrangement before the policy: who employs, who approves the captain, and which policy would answer an injury. Shore staff are a workers' compensation question, handled separately.
Speak with Roberto.
Roberto Guerrero · President and Principal Agent · Licensed agent